Whale stablecoin loops, re-read from the chain
A University of Zurich study finds whales looping sUSDe, sUSDS and syrupUSDC at 5–8x on Aave and Morpho, with thin health factors and no liquidations. We read the same markets on 21 October: sUSDe on Aave Core is down to $124M from $1.67B, the loop's carry against USDC cleared half a point in three of the last sixteen months, and Aave's risk stewards moved the USDe base rate from 0% to 6.3% in two weeks. Plus the venues, oracles and exits the study leaves out.
Krzysztof Gogol, Dawid Rymarczyk and Igli Kristo published How Whales Loop Yield-Bearing Stablecoins, Step by Step today. It draws on a University of Zurich study by Kristo, Rymarczyk, Claudio Tessone and Gogol that replays every supply, withdraw, borrow and repay on Aave v3 and Morpho Blue for sUSDe, sUSDS and syrupUSDC between March 2024 and June 2026, with a holder snapshot on 14 July 2026.
Their findings, in their numbers: 26 Aave borrowers in the 5–8x band hold $275.2M of sUSDe and 48 above 8x hold $118.9M, while 83.7% of borrowers sit at 1.1x or less. Leverage changed on 7.2% of the 2,506 looper-days they observed. On Aave, 13.1% of the positions with a health factor below 1.05 hold 97.0% of that band's collateral; on Morpho, 22.0% hold 93.1%. The lowest health factor they saw was 0.998. No position in the sample was liquidated.
The study is careful and the data work is real. It also stops at 27 June, and these markets have moved since. We read Aave v3 Core, Morpho Blue and the oracles behind both on 21 October 2026, 11:00 UTC, and three things stand out:
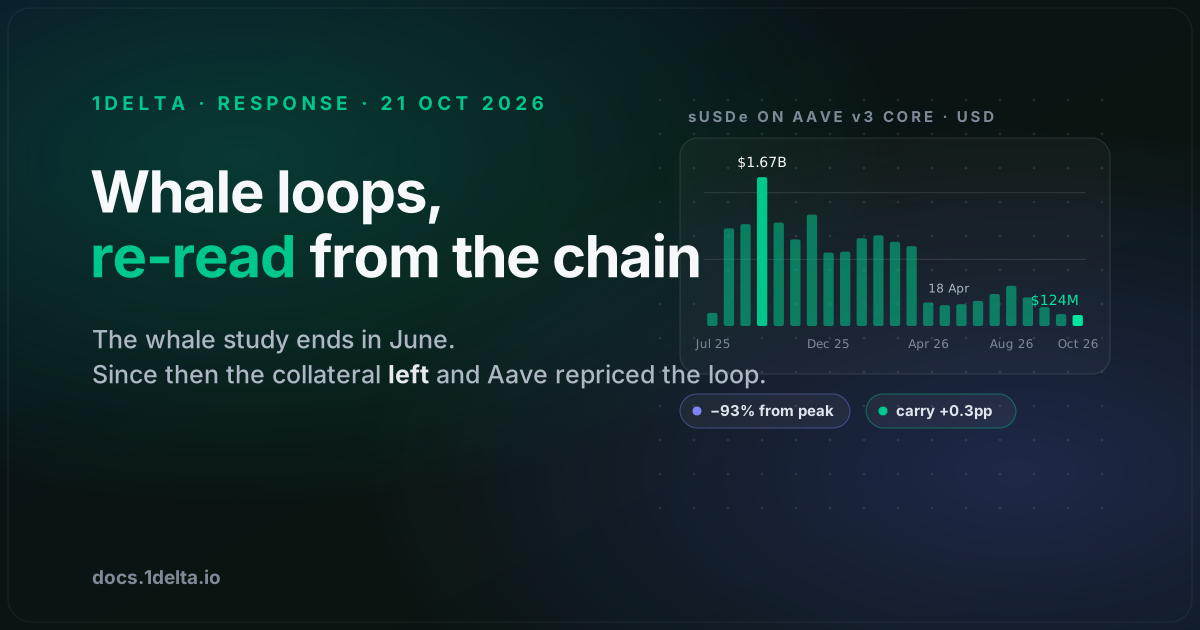
- The collateral left. sUSDe supplied to Aave v3 Core on Ethereum is $124M today. It was $360M in the week of the study's snapshot and $1.67B at its peak on 26 September 2025.
- The carry was thin. Since July 2025, sUSDe's yield has exceeded Aave's USDC borrow rate by more than half a point in three months out of sixteen, all of them in 2025.
- Aave is now pricing the USDe loop out. Between 28 August and 9 September, Aave's risk stewards raised the USDe base borrow rate from 0% to 6%, then to 6.3%, anchored to sUSDe's own yield. The reserve reads 6.6% today at 4.7% utilisation.
The rest of this piece goes through the venues, the oracles, the exits and the strategies the study does not cover. Every figure is read from the chain or an API unless a source is named.
The collateral moved while the paper was in review
The study's Aave numbers come from a single snapshot. The aToken for sUSDe on Aave v3 Core, read every three weeks since July 2025 and valued at that day's sUSDe exchange rate, looks like this:
totalSupply of aEthsUSDe and convertToAssets on sUSDe at each block. Shaded: the two weeks in which the USDe base rate went from 0% to 6%.Three moves are worth dating.
April 2026. On 18 April an attacker released 116,500 rsETH through Kelp DAO's bridge without depositing anything and borrowed against it on Aave. Aave froze rsETH and took bad debt estimated at up to $230M by CoinDesk. Depositors pulled more than $5B in a day. sUSDe on Core went from 732M tokens on 3 April to 216M on 24 April, and total sUSDe supply from 2.88B to 1.81B. Nothing about sUSDe changed. A loop at 8x in a market whose stablecoin side is being withdrawn is a loop whose borrow rate is about to spike, and the sampled USDC borrow rate on 24 April was 8.8%, USDT 13.9%.
The study's window. The snapshot on 14 July falls in the recovery: 290M sUSDe ($360M) on 17 July, 363M ($452M) on 7 August. The report gives $587.1M of sUSDe collateral backing stablecoin debt on Aave. We could not reconcile that with the Core aToken; the Prime instance held under 6M sUSDe at every read and the V4 Ethena market did not exist yet. The methodology section does not say which instances or wrappers are counted, so we leave the two numbers side by side.
September and October 2026. LlamaRisk, acting as Aave risk steward, raised the USDe base rate from 0.00% to 6.00% in six steps between 28 August and 9 September and proposed 6.30% on 11 September, with the base explicitly "anchored to Ethena's realized sUSDe yield" and reassessed weekly. The rate strategy for the Core USDe reserve now reads a base of 6.6% and a slope of 0.25% to the 90% kink, so the floor on borrowing USDe is above what sUSDe pays. LlamaRisk's own table has USDe debt on Core falling from $450.4M on 28 August to $117.5M on 11 September; the variable debt token reads $12.1M today against $255M supplied. sUSDe collateral on Core fell from $452M to $124M over the same weeks.
The base rate targets USDe debt, and the sUSDe e-mode on Core does not lend USDe at all: category 2, "sUSDe Stablecoins", allows USDC and USDT as debt and nothing else, at 90% LTV, 92% liquidation threshold and a 4% bonus. Outside e-mode, sUSDe has an LTV of zero. So the sUSDe loops the study describes on Aave are, by construction, sUSDe against USDC or USDT. Which brings up the carry.
The carry the loop actually earned
The report's yield table assumes a carry of +1.86 percentage points. Here is the monthly average of sUSDe's yield next to the Aave v3 Core borrow rate for the three debt assets, from July 2025 to today. sUSDe yield is DefiLlama's daily series; the borrow rates are the reserve's variable rate read from the Pool contract every two days.
Against USDC, the loop cleared half a point in July, August and September 2025 and in no month since. At 8x, a carry of +0.3 points is 2.4 points of extra yield on the equity before gas, slippage and the cost of the 7.2% of days on which the position is touched. A carry of −1.1 points, as in April 2026, is a levered loss.
Against USDe the picture is different, and it explains why USDe debt is the thing Aave just repriced. From November 2025 to March 2026 and again from June to August, borrowing USDe cost 0.6 to 1.3 points less than sUSDe paid. That carry belonged to the PT e-modes: Core lists five "PT-sUSDe / USDe" categories at 92% LTV, and USDe is what the Plasma deployment's reserve lends. It is the loop the base rate now puts at −1.7 points.
The study reads the whales' calm as diligence. Part of it is a different arithmetic: a position that costs more to adjust than the carry earns in a month gets adjusted once.
Where the loops are today
The study covers Aave and Morpho on Ethereum. That is where the sUSDe loops were in 2025. Today the collateral sits in more places, and the biggest single venue for sUSDe is not on Ethereum.
| venue | collateral | supplied | debt side | max LTV / LLTV | borrow rate |
|---|---|---|---|---|---|
| Aave v3, Plasma | sUSDe | $182.3M | |||
| Aave v3 Core, Ethereum | sUSDe | $123.7M | USDC, USDT | 90 / 92 | 4.48% / 4.08% |
| Aave v3 Core, Ethereum | syrupUSDT | $114.8M | USDC, USDT | 90 / 92 | 4.48% / 4.08% |
| Morpho, Ethereum | sUSDe | $116.6M | PYUSD (97%), DAI, USDtb | 86–91.5 | PYUSD 4.15% |
| Morpho, Ethereum | sUSDS | $70.5M | USDT | 96.5 | 2.75–2.93% |
| Morpho, Ethereum | syrupUSDC | $62.8M | PYUSD | 91.5 | 4.50% |
| Aave v3, Plasma | syrupUSDT | $57.3M | |||
| Kamino, Solana | syrupUSDC | $54.4M | USDC | ||
| Morpho, Ethereum | PT-sUSDS 26 Nov 2026 | $28.6M | USDC, USDT, USDS | 91.5 | 3.8–7.6% |
| Morpho, Ethereum | PT-sUSDe 26 Nov 2026 | $8.3M | USDC | 91.5 | 4.34% |
| Aave V4, Ethereum | sUSDe (Ethena market) | $4.3M | USDe, stables | ||
| Euler v2, Ethereum | sUSDe, syrupUSDC | $1.4M | USDC | ||
| Fluid, Ethereum | sUSDe, syrupUSDC | $0.8M | USDC, USDT |
Aave, Morpho, Euler and Fluid rows read through the 1delta API and Morpho's GraphQL API; Kamino from DefiLlama. Blank cells are parameters we did not read.
Three things in that table are not in the study. Aave's deployment on Plasma, the USDT chain from our stablecoin-native chains piece, holds more sUSDe than Core does. Maple's USDT token on Aave Core, syrupUSDT, is almost twice the size of the syrupUSDC market the study measures on Morpho, with its own 90/92 e-mode. And Morpho's sUSDe loops are now PYUSD loops: $112.7M of the $116.6M of sUSDe on Morpho sits in the PYUSD market, not a USDC one, because that is where the debt was cheapest when they were opened.
The sUSDS row shows what Morpho is for. Sky's token pays 3.80% today and USDT on Morpho costs 2.75%, so the carry is +1.05 points at a 96.5% LLTV, where the largest position runs 11.8x. On Aave Core, USDT costs 4.08% and the same loop loses money. Whales do not stay on one venue because they like it; they stay where the debt is cheapest at the leverage they want.
Concentration, counted today
The study's concentration finding is the one that holds up best. We pulled every open borrow position in the four Morpho markets above.
| market | positions | collateral | positions ≥ $1M | share of collateral | HF < 1.05 | largest position |
|---|---|---|---|---|---|---|
| sUSDe / PYUSD | 31 | $112.7M | 12 | 99% | 7 positions, $23.1M | $23.0M at 6.9x, HF 1.073 |
| sUSDS / USDT | 89 | $70.5M | 9 | 88% | 23 positions, $14.3M | $35.0M at 11.8x, HF 1.054 |
| syrupUSDC / PYUSD | 18 | $62.8M | 5 | 97% | 2 positions, $54.6M | $50.9M at 9.1x, HF 1.029 |
The syrupUSDC market is one address. It holds $50.9M of the market's $62.8M of collateral at 9.1x, with a health factor of 1.029, which at a 91.5% LLTV is 2.8% of collateral value from liquidation. The second-largest sUSDS position sits at 12.9x and 1.046. These are the "thin buffers" of the study, and they are still there.
The other side of concentration is who lends. Morpho markets are funded by curated vaults, and a vault that sees a single borrower at 9x with a health factor of 1.03 can cap its allocation or exit. The study treats the lender side as given. It is a decision someone makes every day.
What the oracle can and cannot do
The study's stress test says a 3–5% fall in sUSDe's price would raise liquidatable collateral on Aave from $40M to over $510M. The sentence assumes the oracle reports a market price. On Aave it does not.
Aave's price source for sUSDe on Core describes itself, on chain, as "Capped sUSDe / USDT / USD". It reads today at $1.25271: the sUSDe exchange rate of 1.25411 times Chainlink's USDT/USD at $0.99888, with a cap on how fast the exchange rate may grow. USDe itself is priced as "Capped USDT/USD". That design went through governance in February 2025 after LlamaRisk showed that under a market feed, $263M of sUSDe collateral became liquidatable at a 2.6% USDe deviation, of which about $1M could be liquidated profitably (the ARFC). Under the USDT peg, liquidations begin at a USDT deviation of about 11%.
So on Aave, a 3% fall in the sUSDe oracle requires either USDT to trade at $0.97 or Ethena to lose 3% of the vault's assets. Secondary-market selling of USDe cannot do it. On 10 October 2025 USDe printed $0.65 on Binance's order book during the largest liquidation day in the market's history; Chainlink's aggregated feed and every on-chain venue stayed near $1, Ethena redeemed about $2B in 24 hours, and Aave's sUSDe positions were untouched (21Shares).
Morpho is market by market. The sUSDe/PYUSD oracle multiplies the sUSDe exchange rate by Chainlink's USDe/USD feed and divides by PYUSD/USD, so it does see a USDe market move, if the aggregated feed moves. The sUSDe/DAI market at 86% has no feed at all: exchange rate only, USDe hardcoded to one DAI. sUSDS/USDT and syrupUSDC/PYUSD follow the first pattern, exchange rate times the underlying's feed. Which oracle a market uses is a parameter of the market, chosen by whoever created it, and the study's health factors mix all of them.
The report's line that "yield-bearing stablecoins rarely lose value" is true of the three it picked. In the same window, four others did not survive. Stream's xUSD went from $1 to $0.26 on 4 November 2025 after a $93M loss at an external manager; Elixir's deUSD, 65% backed by loans to Stream, went to about $0.015 two days later; Stables Labs' USDX broke below $0.60 the same week. Lending markets on Morpho, Euler and Silo priced xUSD at a hardcoded $1, so nothing liquidated and the lenders ate it; analysts traced about $285M of debt across the affected vaults (Pharos). Resolv's USR followed on 22 March 2026 when an attacker minted roughly 80M unbacked tokens and the Curve pool printed $0.025 (Yahoo Finance). Morpho's API still reports bad debt on the USR, deUSD and sdeUSD markets today. The whales' calm rests on the issuer, and in 2025 and 2026 issuers failed at a rate of about one a quarter.
Exits: cooldowns, queues and callbacks
The study scores exits by whether an address has ever used a flash loan: 18.5% of Aave whales, none of the Morpho whales. Two things about that.
Morpho Blue does not need an external flash loan to unwind. Its repay, supplyCollateral and withdrawCollateral calls take callbacks, and the protocol has a zero-fee flashLoan of its own, so a position can be closed in one transaction without a flash-loan event ever appearing at the address. 1delta's composer takes its flash liquidity from the cheapest source available, and on Ethereum that is often Morpho's own zero-fee flash loan. A metric that counts Aave-style flash loans will read Morpho loopers as having no atomic exit when they have the cheapest one.
The harder constraint is what you are selling. sUSDe's unstake cooldown reads 86,400 seconds on chain today, 24 hours; redemption is not instant, so an atomic unwind sells sUSDe into DEX liquidity. syrupUSDC withdrawals go through Maple's queue: maxWithdraw for the $50.9M position returns 0 today. The whale at 9.1x and HF 1.029 cannot redeem its way out inside one block; it can only sell. The exit mechanism on the protocol side is solved. The exit on the asset side is a liquidity question the study does not ask, and it is the one that decides whether a liquidation at HF 1.00 is a 3% haircut or bad debt.
Strategies the study leaves out
The loop in the report is the simplest one. Most of the leverage on yield-bearing dollars in the last eighteen months was something else.
PT loops. When Chaos Labs sized Aave's Ethena exposure in August 2025, looped debt against PT tokens was $3.5B against $550M of sUSDe-against-stable loops (Chaos Labs). A PT fixes the yield, so the carry is known at entry, and the collateral converges to par at maturity. The cost is a second oracle problem, PT discount risk, which we wrote up when a 1% move in a PT price liquidated $36.1M on Morpho in August. Today PT-sUSDe for 26 November trades at a 4.96% implied yield and PT-sUSDS at 5.32%, against 4.79% and 3.80% on the floating tokens; the PT-sUSDS loop against USDS on Morpho carries about +1.5 points for five weeks.
Choosing the debt, not the venue. The same sUSDe collateral can borrow USDC at 4.48% on Aave, PYUSD at 4.15% on Morpho, or USDT at 2.75% on Morpho if you hold sUSDS instead. A debt swap moves an open position from one debt asset to another without closing it, and a migration moves it between protocols; both are single transactions on 1delta. The study's finding that leverage rarely changes may partly reflect that the borrowers who did reoptimise did it by moving, and a move shows up as a new position elsewhere, not as a leverage change.
Fixed-rate debt. The thing a looper fears most is the April 2026 pattern: the borrow rate doubling while the yield does not. Morpho Midnight on Base and Term Finance's auctions lend at a fixed rate to a fixed date, which turns the carry into a number. Coverage is still thin for these tokens, and it is where a cautious loop should look first. Our fixed-term lending piece has the mechanics.
Soft liquidation. Curve's LlamaLend accepts sUSDe and syrupUSDC against crvUSD and liquidates continuously across a price band instead of at a threshold. The markets are small today, $1.4M and $1.8M, but the design answers the study's concentration problem directly: a $50M position does not get sold in one block.
Other chains. Aave on Plasma and Kamino on Solana already hold more of this collateral than Euler and Fluid on Ethereum combined. Rates, oracles and e-modes differ per deployment, and the only way to compare them is a normalised read across all of them, which is what the 1delta API exists to do.
Four checks to add to the whale checklist
The report ends with a seven-point checklist: carry, leverage, buffer, penalty, oracle, exit, concentration. From this week's reading we would add four.
- Who can move the borrow rate, and how fast. Aave's risk stewards took the USDe base rate from 0% to 6.3% in fourteen days without a governance vote. A loop's carry is a parameter someone else controls.
- What the oracle is made of. Exchange rate times a peg, exchange rate times a market feed, or exchange rate alone. Each fails differently, and the one that cannot be liquidated by a market move is also the one that cannot be liquidated by an issuer failure until someone updates it by hand.
- How the collateral is sold, not just how the loan is closed. A 24-hour cooldown or a withdrawal queue means the atomic exit is a DEX sale. Size the position against that pool's depth, not against the lending market's LLTV.
- How much of the carry is incentives. Ethena's liquid leverage programme went from 27% to 47% of USDe fee allocation between July and September (Ethena governance). Carry paid by a token programme ends when the programme does.
Running loops across these venues
The venue table above is two data calls: /v1/data/lending/pools for every market on a chain with its rates, caps and oracle description, and /v1/data/lending/pairs/leverage for every collateral-debt pair with its maximum leverage and liquidity. The write side is the same shape: /v1/actions/loop/leverage opens a loop in one transaction against Aave, Morpho, Euler, Fluid or any other lender the API indexes, /v1/actions/loop/close unwinds it, and debt-swap and migrate move it when the carry does. The API reference has every endpoint; the actions article walks through the request shape.
Sources: How Whales Loop Yield-Bearing Stablecoins, Step by Step · Recursive Leverage in Yield-Bearing Stablecoins, UZH · LlamaRisk, IRM changes 11 September 2026 · Aave ARFC, sUSDe and USDe price feed update · Chaos Labs, Aave's growing exposure to Ethena · Ethena governance update, Q3 2026 · CoinDesk on the Kelp DAO exploit · 21Shares on the Binance USDe depeg · Pharos on Stream, Elixir and USDX · Yahoo Finance on Resolv USR · Morpho API · DefiLlama yields · 1delta API